A Seattle condo’s monthly dues tell only part of the ownership story. Special assessments can affect affordability, negotiations, financing, and future resale, so buyers and sellers benefit from asking direct questions before an offer or listing goes live. The key is not simply whether an assessment exists, but what work it funds, how the association plans to collect it, and what may still be ahead.
Why Special Assessments Deserve a Closer Look
Condominium living can simplify certain maintenance responsibilities because owners contribute to the care of shared building elements through regular homeowners association dues. Those dues may support insurance, reserves, management, utilities, landscaping, common-area upkeep, and planned repairs. A special assessment is different: it is an additional charge approved by the association to cover an expense that is not fully funded through the operating budget or reserve account.
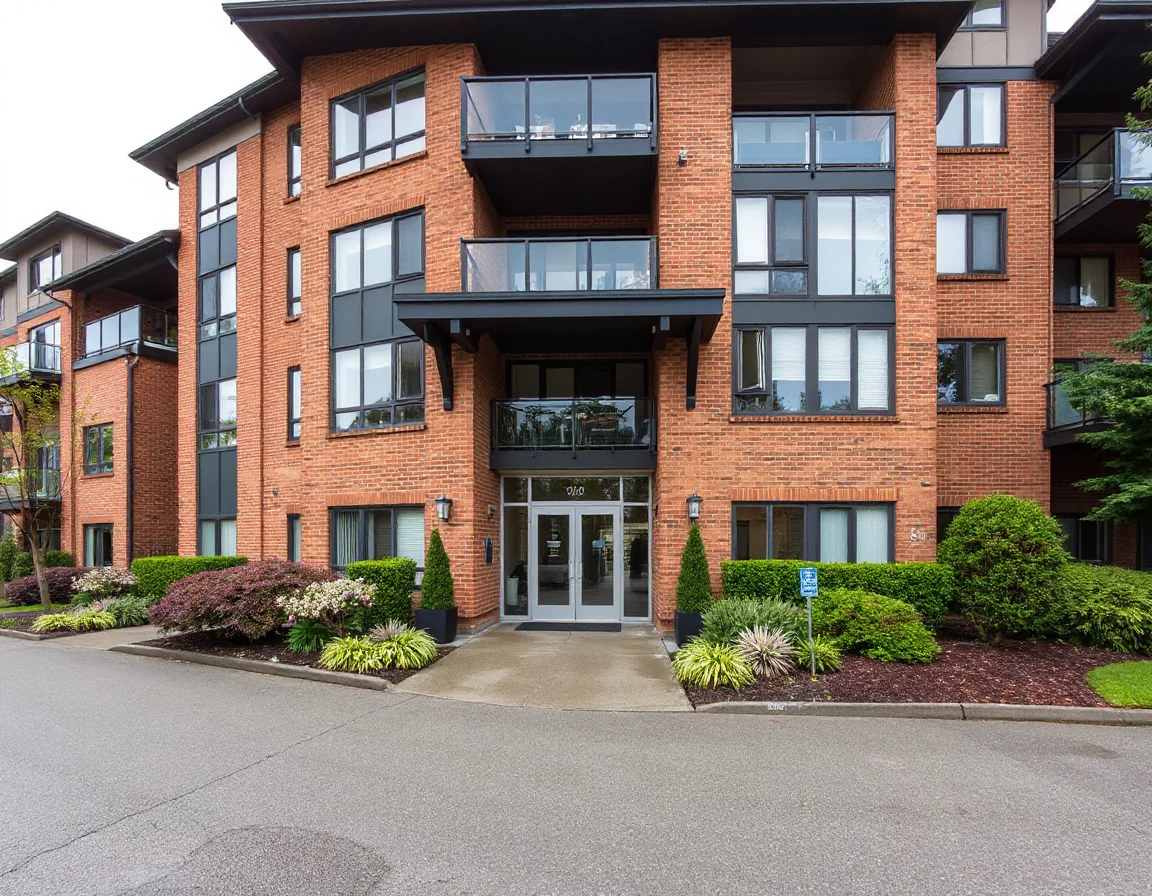
In Seattle, assessments can arise from projects such as roof replacement, elevator modernization, exterior envelope repairs, plumbing work, parking-garage maintenance, fire-safety upgrades, or a higher-than-expected insurance expense. Older buildings may face substantial capital projects as components reach the end of their useful lives, while newer communities can encounter construction-related repairs, changing insurance requirements, or reserve funding adjustments.
The presence of an assessment does not automatically make a condo a poor choice. In many cases, it reflects an association addressing necessary work rather than postponing it. Still, the amount, payment schedule, scope of work, and condition of the association’s finances can materially affect a buyer’s total cost of ownership. A seller who understands these details early is also in a stronger position to prepare accurate disclosures and respond clearly to questions.
A large assessment paired with a well-defined repair plan can be easier to evaluate than a smaller charge with no clear scope, timeline, or funding strategy.
Washington condominium transactions commonly involve a resale certificate and association documents that provide important information about dues, assessments, budgets, insurance, reserves, rules, and pending matters. Buyers should allow enough time to review these materials carefully and discuss questions with qualified real estate, legal, lending, and inspection professionals as appropriate. The documents tell a more complete story than a listing’s monthly HOA figure alone.
Questions Buyers Should Ask Before Moving Forward
Start with the most direct question: Is there a current special assessment? Ask for the total amount, the individual unit’s share, the remaining unpaid balance, the due dates, and available payment options. Some associations allow a lump-sum payment, while others establish installments over months or years. Confirm whether interest applies to installment payments and whether any balance can become due at sale, refinance, or another specified event.
Next, ask what the assessment funds and where the project stands. Is the work planned, underway, or complete? Has the association signed contracts? Are permits required? Is there a contingency in the budget? A project that has been carefully scoped and competitively bid may carry a different level of uncertainty than one still being evaluated. Meeting minutes can be particularly useful because they may reveal discussions about bids, contractor timing, engineering reports, insurance issues, or owner concerns.
Buyers should also look beyond the current assessment. Review the reserve study, reserve balance, annual budget, recent financial statements, and board meeting minutes for signs of deferred maintenance or upcoming large expenditures. No document can predict every future cost, but these materials can help identify whether key systems have been recently updated, whether reserves appear aligned with anticipated projects, and whether the association has a pattern of frequent assessments.
Financing deserves its own conversation. Depending on the loan program, property type, project status, and amount of the assessment, a lender may have additional questions about the condominium association. A lender can explain how an assessment affects debt-to-income calculations, required cash to close, or project review. Getting that discussion underway early can prevent an unwelcome surprise after an offer has been accepted.
- What is the assessment amount for this specific unit?
- What repair, replacement, or expense does it cover?
- Has the association approved contracts and a project schedule?
- What is due before closing, and what remains due afterward?
- Are other assessments under discussion in recent meeting minutes?
- How are reserves, insurance deductibles, and major maintenance projects being managed?
How Sellers Can Prepare for Assessment Questions
Sellers are often best served by gathering association information before marketing begins. A prospective buyer is likely to ask about current dues, special assessments, reserve funding, insurance, recent repairs, and planned projects. Having the resale certificate, assessment notice, payment schedule, relevant meeting minutes, and project information organized can make conversations more efficient and reduce uncertainty during the due-diligence period.
Clarity matters more than spin. If an assessment is funding a major building improvement, explain the objective facts: the project scope, anticipated timeline, amount allocated to the unit, payment status, and available association documentation. Avoid minimizing a known expense, but also avoid assuming that every buyer will view it the same way. Some purchasers may value completed work and improved building systems; others may focus on near-term cash requirements. Transparent information lets each party evaluate the opportunity based on their own priorities.
Negotiating responsibility for an assessment is separate from understanding the assessment itself. Depending on the purchase agreement, timing, local practice, lender requirements, and the parties’ negotiations, a seller might pay some or all of an assessment at closing, offer a credit where permitted, adjust pricing, or leave future installments with the buyer. There is no universal answer. The important step is to define the obligation precisely and put the agreed treatment in the contract documents.
For a seller, an assessment can also influence pricing strategy. The list price should be considered in the context of the unit’s condition, location, comparable sales, monthly dues, assessment terms, and current competition. A careful market analysis helps avoid treating the assessment as an isolated number. Buyers compare the full financial picture, including what they will pay at closing and what they expect to spend after receiving the keys.
Before listing, ask the association whether an assessment is fully approved, whether the unit has an outstanding balance, and whether any additional capital work is currently being considered.
Read the Building Story, Not Just the Monthly Dues
A low HOA fee can look attractive at first glance, but it is not automatically a sign of lower long-term costs. Fees that are too low to support operations, reserves, insurance, and expected maintenance may create pressure later. Conversely, higher dues may reflect services, staffing, utilities, amenities, insurance, or a deliberate reserve contribution. The useful comparison is not simply low versus high; it is whether the association’s budget and planning appear understandable and sustainable for the building.
Seattle’s wet winters, changing temperatures, and dense urban building environment place real demands on roofs, windows, decks, drainage systems, façades, and garages. Building age, construction type, past repairs, and maintenance history all matter. Buyers may wish to coordinate their document review with an inspection of the unit and, where appropriate, obtain professional guidance on concerns raised by association records. Sellers can benefit from reviewing the same information early, before a buyer uncovers a question that could have been anticipated.
It is also wise to distinguish between an assessment that has been formally adopted and a future possibility mentioned in meeting minutes. Boards routinely discuss maintenance needs before making decisions. Those discussions are valuable context, but they are not necessarily a final charge. Ask what has been approved, what is being studied, what funds are available, and when the association expects to make decisions. Specific dates, votes, estimates, and written notices are more useful than assumptions.
A Practical Path to a More Confident Condo Transaction
Special assessments are one part of responsible condo ownership, not a reason to skip a building automatically. The strongest decisions come from reviewing the numbers alongside the project details, reserve planning, association records, financing implications, and terms of the purchase agreement. Whether you are buying or selling, build time into the process for questions and written documentation.
Northwest Premier Brokers can help clients frame the right real estate questions, compare Seattle-area condo opportunities, and coordinate the transaction process with the appropriate professionals. With a clear understanding of assessments and association health, buyers and sellers can approach the next step with fewer surprises and a more complete picture of the property.